
Japan and the United States were the largest destinations, accounting for about 25% and 23% of volume respectively.
Japan and the United States were the largest destinations, accounting for about 25% and 23% of volume respectively.

Survey and industry data show firms improve efficiency, but sector productivity diverges from sawmills as technical change remains weak and variable.
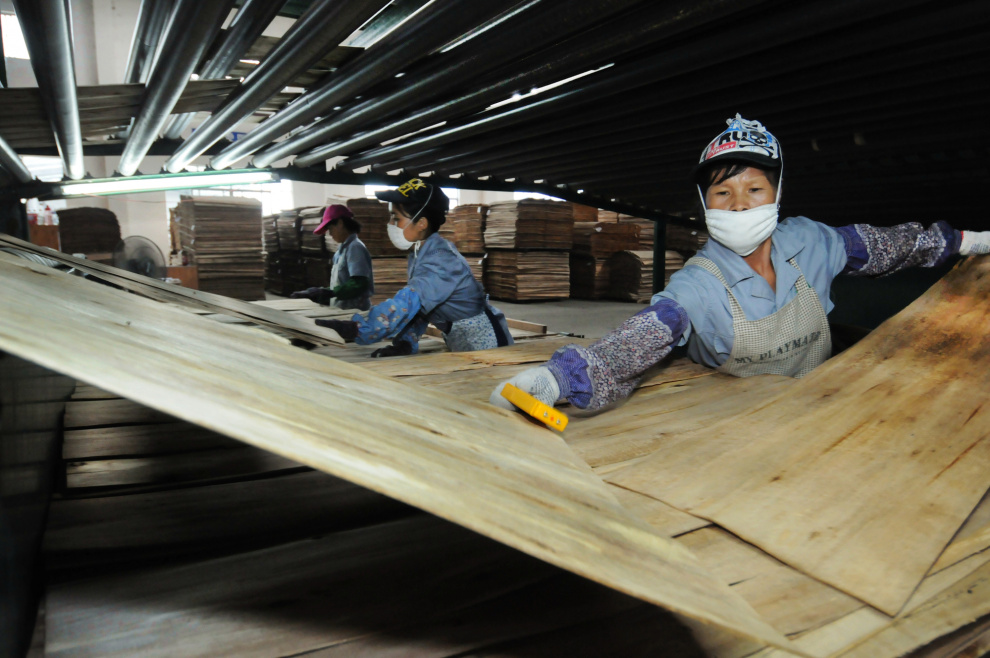
Price for plywood imported to Japan dipped 3%.

Compared with the previous month, production was down 5%.
Wood processing, furniture manufacturing and construction-linked non-metal mineral products record profit declines even as industrial profits and margins increase.
Compared with the previous month, production was down 1.1%.
Japan became the largest destination after U.S. duties hit Indonesia’s shipments.
Price for plywood imported to Mexico rose 4%.
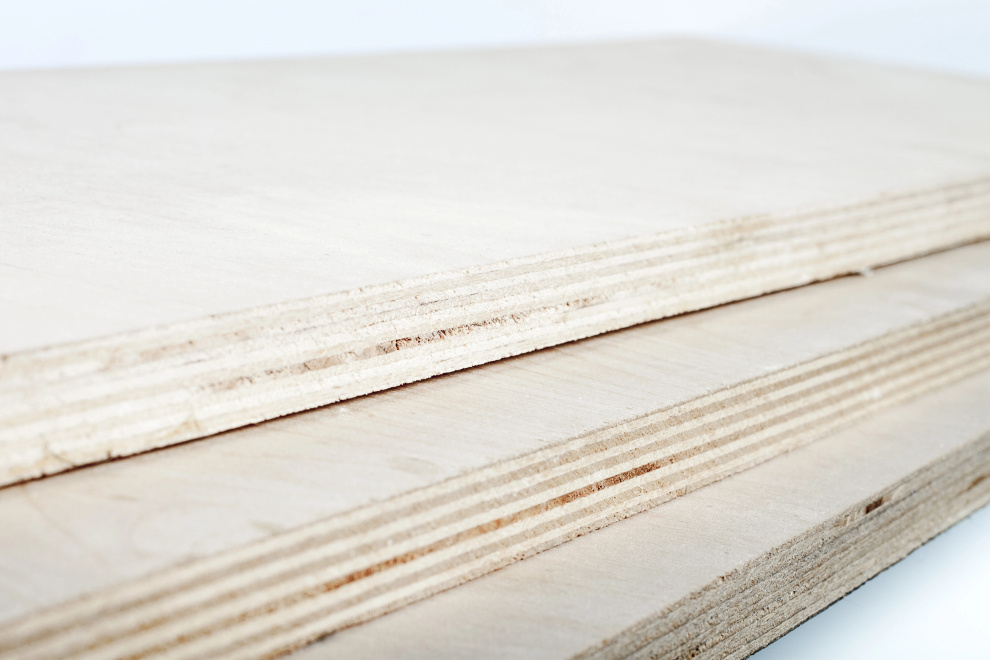
Price for plywood exported from Russia to China decreased 9%.
Price for plywood exported from China gained 5%.
Price for plywood imported to the UK contracted 15%.

Price for plywood imported to Kazakhstan decreased 5%.

Two biggest single-project awards fund curved glulam output and wood-fibre foam capacity.

Hardwood lumber, millwork and plywood prices also increased.

Price for plywood exported from Brazil increased slightly 0.5%.

Price for plywood exported from Chile slipped 1.6%.
Interim Chief Commercial Officer since November 2025 remains on Group Executive Board and reports to CEO Mika Saariaho.
Price for plywood exported from Russia to the U.S. declined only 0.6%.

Volatile mortgage rates, weather disruptions, and cautious housing demand weigh on results and margins, with the largest pricing and gross-margin pressure in engineered wood products.

Lumber sales realizations rise 13% from fourth-quarter averages and oriented strand board realizations rise 8%.